Every year, headlines predict the imminent collapse of Social Security, painting a picture of a system on the brink of bankruptcy. This persistent narrative creates anxiety for millions of Americans planning their future. But what if the real story is less about an empty vault and more about a solvable, long-term math problem? The fear of benefits disappearing entirely often stems from a core misunderstanding of how the system is designed and funded.
At its core, Social Security operates as a pay-as-you-go system, where contributions from today’s workers and employers directly fund the benefits of current retirees. The surplus funds collected over the decades are held in special trust funds, which are now facing pressure from a major demographic shift. With people living longer and birth rates declining, the ratio of workers paying into the system versus retirees drawing from it has changed dramatically since the program’s inception.
This guide cuts through the political noise and financial jargon. We will decode what the official ‘trust fund depletion’ projections actually mean for your future benefits—and what they don’t. We’ll explore the demographic forces straining the system, analyze the real solutions policymakers are debating, from tax adjustments to changing the retirement age, and provide a clear, personal action plan. By the end, you’ll be equipped not with fear, but with a strategic understanding to future-proof your own retirement plans.
Decoding the Social Security Trust Funds: What They Are and Why They Matter
Headlines scream about Social Security going “bankrupt,” but what most people miss is how the system actually works. The program isn’t a single giant piggy bank. Instead, it operates through two major government accounts, collectively known as the Social Security trust funds. These funds are primarily financed by payroll taxes—that FICA deduction on your paystub—paid by current workers and their employers.
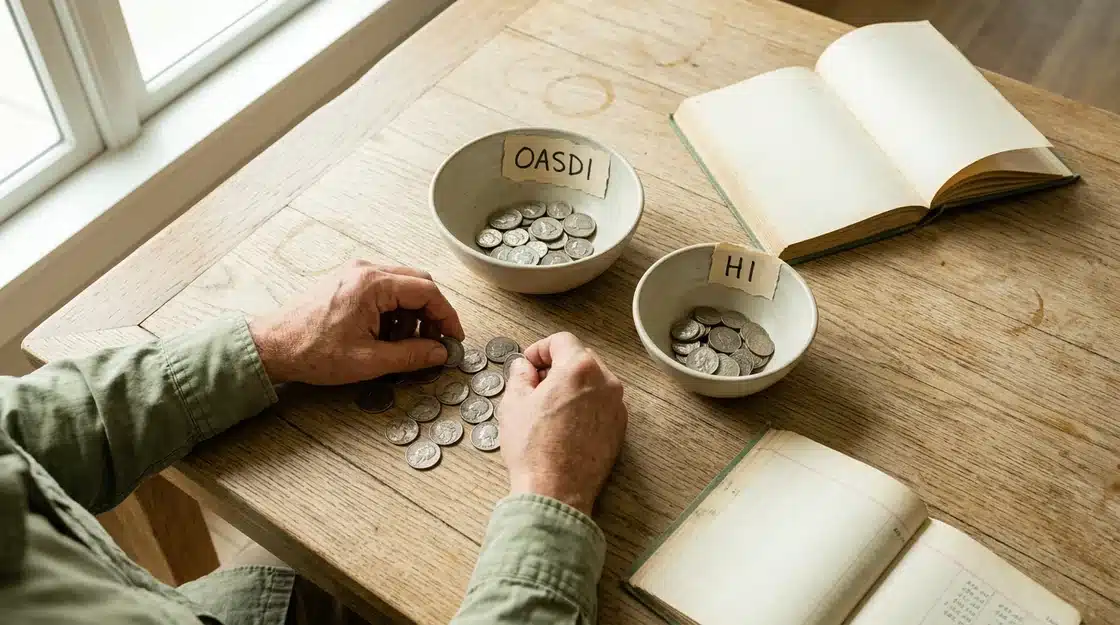
Think of it like having two separate jars for household expenses. The first and larger jar is for the OASDI (Old-Age, Survivors, and Disability Insurance) program, which pays for retirement and disability benefits. The second, smaller jar is for the HI trust fund (Hospital Insurance), which covers Part A of Medicare. According to the Social Security Administration, workers and employers each contribute 6.2% of wages to OASDI and 1.45% to HI, creating a constant inflow of money.
These are not personal savings accounts. The money you pay in today is immediately used to pay benefits for current retirees and other recipients. It’s a pay-as-you-go system, where today’s workforce, from those in federally funded apprenticeships to seasoned professionals, supports the current generation of beneficiaries. This continuous flow is required for the system’s stability.
The funds themselves are essentially government ledgers, tracking the surplus taxes collected over the years, which are then invested in special U.S. Treasury securities. The operation of these funds shares principles with the wider U.S. budget, a complex process detailed in our guide to federal appropriations. The real debate isn’t about an empty vault, but about a projected shortfall where future benefit payments are expected to exceed incoming tax revenue.
Understanding Depletion Projections: Key Dates and What They Really Mean
You’ve probably seen the alarming headlines declaring that Social Security is going bankrupt. This is a basic misunderstanding of how the system works. The Social Security trust fund depletion projections do point to a future shortfall, but “depletion” doesn’t mean the money vanishes overnight. It’s more like a household’s long-term savings account running dry, forcing it to rely solely on its monthly income.
That monthly income for Social Security is massive. It comes from payroll taxes on current workers. Even after the trust funds are exhausted, the Social Security Administration projects that ongoing tax revenues would still be able to pay a significant portion of promised benefits. This is the single most important fact to grasp.
Comparing Official Projections: Trustees vs. CBO
Two main government bodies issue the key actuarial reports that inform these timelines: the Social Security Administration’s Board of Trustees and the Congressional Budget Office (CBO). While their methodologies differ slightly, their conclusions are broadly similar. They both analyze demographic trends, economic growth, and wage projections to forecast the future.
The Trustees’ Report typically projects that the combined trust funds for retirement and disability benefits will be depleted in the early-to-mid 2030s. The CBO’s analysis, which is part of its role in informing Congress about the complexities of federal budget appropriations, often projects a similar date, sometimes a year or two earlier. These dates shift slightly with each annual report based on the latest economic data—things like workforce participation rates, which are influenced by trends in education and vocational training, such as the growing interest in federally funded apprenticeship programs.
The important thing is not the exact year, but the consensus that a shortfall is on the horizon without congressional action.
What ‘Depletion’ Actually Implies for Your Benefits
Let’s be crystal clear: trust fund depletion is not a financial apocalypse for retirees. It is a serious problem that requires a solution, but it does not mean checks stop arriving. The data suggests—though not conclusively—that even after the Social Security depletion date passes, incoming payroll taxes would be sufficient to cover about 78% to 80% of promised benefits.
So, what does this actually mean for your benefits? It means that if Congress does nothing, future retirees would receive a benefit cut. A 20% reduction is a significant hit, but it is a far cry from the 100% loss that many people fear. Think of it this way: the system has a primary income source (payroll taxes) and a savings account (the trust funds). Depletion just means the savings account is empty, forcing the system to operate only on its current income.
This projected funding gap is precisely why lawmakers regularly discuss reforms. The real question isn’t whether Social Security will exist, but rather what combination of adjustments—like changes to the full retirement age or tax rates—will be enacted to ensure its solvency for generations to come.
The key takeaway from our projections is not that Social Security is going bankrupt. The system has a dedicated revenue stream that will continue to finance a majority of benefits even after the trust funds are depleted, but legislative action will be needed to avoid a sharp reduction in payments.
— Phillip Swagel, Director of the Congressional Budget Office
| Solution Type | Specific Proposal | How It Works | Potential Impact |
|---|---|---|---|
| Increase Revenue | Raise the Payroll Tax Rate | Gradually increase the 12.4% FICA tax rate paid by employees and employers. | Directly increases funds but reduces take-home pay for workers and raises costs for businesses. |
| Increase Revenue | Lift the Earnings Cap | Tax all or a higher portion of annual income, removing the current cap. | Significantly boosts revenue from high earners but may be opposed as a targeted tax increase. |
| Modify Benefits | Adjust COLA Formula | Switch to a less generous inflation measure, like Chained CPI, for annual adjustments. | Slows the growth of benefit payouts over time, but may reduce the purchasing power of retirees. |
| Change Eligibility | Raise Full Retirement Age | Gradually increase the age to claim full benefits from 67 to 69 or 70. | Effectively reduces lifetime benefits and encourages longer careers, but disproportionately affects those in physically demanding jobs. |
Factors Driving the Trust Fund Challenges: A Closer Look
The Social Security math problem isn’t some complex conspiracy; it’s a simple, brutal demographic equation. For decades, a large base of workers paid taxes to support a smaller group of retirees. That ratio is flipping. The system was designed in an era with entirely different population dynamics, and what most people miss is how profoundly three key trends are straining its finances.
The core of the issue boils down to a few powerful forces working in concert. These aren’t temporary problems but long-term shifts in American society. They are the primary drivers of the projected shortfalls.
- Declining Birth Rates: The U.S. total fertility rate has been hovering around 1.7 births per woman, according to the Social Security Administration’s own reports. This is well below the “replacement level” of 2.1 needed to keep the population stable without immigration. Fewer births today mean fewer workers paying into the system tomorrow.
- Increased Life Expectancy: When Social Security began in 1935, the average life expectancy was just under 62 years. Today, it’s closer to 77. People are, thankfully, living longer, healthier lives, but this means they are collecting benefits for many more years than the system’s architects ever anticipated.
- Slower Wage Growth: Economic productivity and wage growth have not kept pace with projections from a few decades ago. Stagnant real wages for many workers mean payroll tax collections—the lifeblood of Social Security—are lower than they need to be. This economic pressure affects everything from retirement savings to decisions about the return on investment for higher education.
Think of it like a pay-as-you-go subscription for a service where the number of users is growing much faster than the number of paying customers. The pool of money is simply being stretched thinner. This isn’t just a retirement issue; it’s a signal about the entire federal budget landscape and the economic pressures on younger generations.
These demographic and economic realities mean that without changes, the system will eventually pay out more than it takes in each year. The question isn’t whether a problem exists, but what combination of adjustments will be made to solve it.
Potential Solutions on the Table: What Policymakers Are Considering
Washington’s playbook for Social Security isn’t filled with magic bullets. The proposed fixes boil down to a few politically painful choices: take in more money, pay out less money, or make people wait longer to get it. Most serious proposals are some combination of these three levers, each with its own set of winners and losers. Understanding these options is the first step to seeing where the debate is headed.
The entire conversation is a masterclass in trade-offs. There are no easy answers here.
Adjusting Revenue: Tax-Side Solutions
One direct way to address the shortfall is to increase the amount of money flowing into the trust funds. The most discussed method involves raising the payroll tax rate, which currently stands at 12.4% of earnings, split between employees and employers. A report from the Congressional Budget Office (CBO) found that increasing this rate by just one percentage point could eliminate over half of the projected 75-year shortfall. The obvious downside is a direct hit to workers’ take-home pay and an increase in labor costs for businesses.
Another popular proposal is to raise the cap on earnings subject to Social Security taxes. Currently, only income up to a certain annual limit ($168,600 as of recent figures) is taxed. Lifting or eliminating this cap would mean high-income earners contribute on a larger portion of their salary. Proponents argue this is a matter of fairness, as it would make the system more progressive. Opponents, claim it would disproportionately tax a small group of earners without a corresponding increase in their future benefits, potentially affecting investment and hiring decisions. This kind of fiscal policy decision is tied into the larger, more complex world of government spending outlined in the federal budget appropriations process.
Modifying Benefits: Expenditure-Side Solutions
The other side of the equation is reducing the amount of money paid out to beneficiaries. This is a delicate subject, as it directly impacts retirees who depend on this income. One approach involves changing the formula used to calculate initial benefits for future retirees. This could be done by increasing the number of years used to calculate average earnings from 35 to 38 or 40, which would typically lower the average for most people and their starting benefit.
A more immediate idea is to adjust the annual Cost-of-Living Adjustment (COLA). This is the yearly increase beneficiaries receive to keep pace with inflation. Some policymakers suggest switching to a different inflation measure called the “Chained CPI” — a bureaucratic term for a slightly less generous inflation gauge — which assumes consumers substitute cheaper goods when prices rise. While the annual difference seems small, the American Academy of Actuaries estimates this change could reduce outlays by about 8% over the long term. But would this seemingly minor tweak leave seniors with less purchasing power over time?
Raising the Full Retirement Age: A Common Proposal
Perhaps the most widely debated solution is to gradually increase the full retirement age (FRA), which is currently set to top out at 67 for those born in 1960 or later. Proposals often suggest raising it to 68, 69, or even 70 for future generations. This is effectively a benefit cut, as it forces individuals to either wait longer to claim their full benefit or accept a permanently larger reduction for claiming early. It’s like training for a marathon only to have the officials move the finish line another mile down the road just as you approach it.
This idea has a simple appeal: people are living longer, so they should work longer. The data suggests life expectancy at age 65 has increased by several years since Social Security’s inception. The underrated factor here, is the stark difference in outcomes. This change would disproportionately affect workers in physically demanding jobs who may not be able to continue working into their late 60s. The career path you choose, whether it’s from a trade school or a traditional four-year degree, has massive implications for how a higher retirement age would impact you personally.
Ultimately, any solution will likely be a hybrid of these approaches, as no single change is politically palatable enough to pass on its own. The real question is which combination of adjustments policymakers will finally have the will to enact.
Your Personal Action Plan: Strategic Steps to Prepare for Future Changes
Relying on politicians to solve the Social Security funding gap is not a retirement strategy; it’s a gamble. While discussions in Washington D.C. continue, your financial future rests squarely in your hands. The time for passive observation is over. Taking proactive, deliberate steps today can build a formidable defense against any future benefit adjustments.
This isn’t about panic. It’s about control. By building a plan that doesn’t treat Social Security as its only support beam, you ensure your retirement remains stable regardless of policy shifts. The following steps are your blueprint for financial resilience.
Diversifying Your Retirement Income Streams
Treating Social Security as your sole retirement plan is like building a house on a single pillar. The original design of the program was to be one part of a three-legged stool: pensions, personal savings, and Social Security. Today, with pensions largely gone for private-sector workers, the other two legs must be stronger than ever. Your primary goal should be to create multiple sources of income for your later years.
The most common tools are employer-sponsored retirement plans like a 401(k) or 403(b), especially if they offer a company match—that’s free money. Beyond that, Individual Retirement Accounts (IRAs), both Traditional and Roth, offer tax-advantaged ways to grow your wealth. The underrated factor here is how your career choices impact your ability to save. For instance, a detailed analysis of a trade school versus a four-year degree can reveal surprising differences in long-term earning and saving potential.
Don’t discount other avenues. Rental properties, dividend-paying stocks, and even part-time work or a small business can provide income streams that are completely independent of government programs. This diversification acts as a important buffer.
Understanding Your Social Security Statement
Your Social Security statement is one of the most important financial documents you will receive, yet many people barely glance at it. You can access it anytime by creating an account on the SSA.gov website. This statement is your personal report card, showing your complete earnings history and projecting your estimated benefits at different claiming ages (62, your full retirement age, and 70).
What most people miss is the importance of verifying their earnings record. The SSA bases your future benefit amount on your highest 35 years of indexed earnings. An error—a year where your income is incorrectly reported as zero, for example—could cost you thousands of dollars over your lifetime. Review this record annually for accuracy and report any discrepancies immediately.
Strategic Claiming: Maximizing Your Future Benefits
When you claim your Social Security benefits is the single most powerful lever you can pull to affect your monthly payment. You can start receiving benefits as early as age 62, but your monthly payment will be permanently reduced. If you wait until your full retirement age (FRA), which is currently 67 for those born in 1960 or later, you receive 100% of your earned benefit. Wait even longer, and your benefit increases.
For every year you delay claiming past your FRA up to age 70, your benefit increases by about 8%. This is a guaranteed, inflation-adjusted return you can’t find in any other financial product. Delaying from 62 to 70 can result in a monthly check that is over 75% larger. It’s a massive difference.
Evaluating Early vs. Delayed Claiming
The decision to claim early or late is deeply personal and complex. Claiming early at 62 provides income sooner, which might be necessary due to health issues, job loss, or a desire to retire early. The math often suggests a “break-even” point, typically in your late 70s or early 80s, where the total lifetime benefits from delaying surpass those from claiming early. But is more money later always better than having cash in hand now?
Consider your health, family longevity, and other available income sources. If you are in good health and have other funds to live on, delaying is often a powerful strategy, especially for the higher-earning spouse in a couple to maximize the survivor benefit. Conversely, if you need the money or have health concerns, claiming early might be the logical choice. There is no single right answer, only the right answer for your specific circumstances.
Monitoring Policy Developments and Advocating for Your Future
Staying ignorant of potential changes is not a defense against them. You don’t need to become a policy expert, but having a basic understanding of proposed solutions is wise. Following reputable news sources and non-partisan organizations like the AARP or the Committee for a Responsible Federal Budget can provide clear summaries of legislative proposals. Understanding the federal budget process gives you context for when and how these changes might actually happen.
This knowledge empowers you. You can contact your elected representatives to voice your opinions on proposals that affect your retirement security. Participating in town halls or signing petitions are small actions that contribute to a larger conversation. Ultimately, your personal financial plan is your best shield, but being an informed citizen is how you help shape the policies that will affect everyone.
The Real Variable: Political Will, Not Empty Coffers
The solvency of Social Security is not, and has never been, a question of financial possibility. The math is straightforward, and the levers for adjustment are well-understood. The true uncertainty lies not in actuarial tables, but in the halls of Congress. The greatest risk to future benefits isn’t demographic change; it’s the persistent political gridlock that delays action and allows the funding gap to widen.
Every proposed solution involves a trade-off, asking some group—whether it’s current workers, high-income earners, or future retirees—to contribute more or receive less. Choosing a path requires a level of political courage that has so far been elusive. This transforms the Social Security debate from a simple accounting problem into a profound question about our nation’s priorities and intergenerational obligations.
So, as you build your personal financial fortress, the most important question to consider may not be when the trust funds will be depleted, but rather, when will our leaders have the will to act? Your engagement in that public debate, demanding a sustainable and fair solution, is as notable as any 401(k) contribution you make.
Frequently Asked Questions
What exactly is the Social Security Trust Fund?
The Social Security Trust Fund isn’t a single bank account. It refers to two government accounts that hold the surplus payroll tax revenue collected over the years. This money is invested in special-issue U.S. Treasury securities, essentially IOUs from the government, which earn interest.
Does ‘depletion’ mean Social Security benefits will stop entirely?
No, depletion does not mean benefits will stop. It means the reserve funds will be exhausted. The system will continue collecting payroll taxes from current workers, and this ongoing revenue is projected to be enough to pay a significant portion—around 78% to 80%—of promised benefits.
When is the Social Security Trust Fund projected to be depleted?
Official government projections consistently place the depletion date for the combined retirement and disability trust funds in the early-to-mid 2030s. This specific year can shift slightly with each new annual report based on the latest economic and demographic data.
How do demographic changes affect Social Security’s solvency?
Demographics are the primary driver of the long-term shortfall. Americans are living longer, meaning they collect benefits for more years than originally anticipated. Simultaneously, lower birth rates mean there are fewer workers paying into the system to support each retiree, straining the pay-as-you-go model.
What can I do now to prepare for potential Social Security changes?
Focus on building your own financial security to reduce reliance on Social Security. Maximize contributions to retirement accounts like a 401(k) or an IRA, especially if your employer offers a match. Creating a diversified retirement plan is the best defense against any future policy adjustments.