Are you ready to take control of your financial future and ensure a comfortable retirement? As we look towards 2026, there’s no better time to evaluate and optimize your 401(k) strategy. For many, a 401(k) is the cornerstone of retirement savings, offering significant tax advantages and the power of compound interest. But simply contributing isn’t enough; to truly maximize your 401(k) 2026, you need a proactive and informed approach. Our goal with this comprehensive guide is to empower you with the knowledge and strategies to potentially boost your contributions and returns by a remarkable 15% or more, securing a stronger financial foundation for your golden years.
The financial landscape is ever-evolving, and staying ahead means understanding the nuances of your retirement accounts. From understanding contribution limits and employer matching to savvy investment choices and tax planning, every decision plays a crucial role. This article will delve deep into actionable steps you can implement starting today to ensure your 401(k) is working as hard as possible for you. Let’s embark on this journey to financial empowerment and unlock the full potential of your retirement savings.
Understanding Your 401(k) Basics for 2026 Optimization
Before we dive into advanced strategies, a solid understanding of the fundamental principles of your 401(k) is essential. A 401(k) is an employer-sponsored retirement savings plan that allows employees to invest a portion of their paycheck before taxes are taken out. This pre-tax contribution reduces your current taxable income, providing an immediate tax benefit. The money then grows tax-deferred until retirement, when withdrawals are taxed as ordinary income.
Key Features of a 401(k):
- Pre-Tax Contributions: Money goes in before income taxes are calculated, lowering your current taxable income.
- Tax-Deferred Growth: Your investments grow without being taxed annually, allowing for faster compounding.
- Employer Match: Many employers offer to match a portion of your contributions, essentially providing free money. This is often the most overlooked aspect of maximizing your 401(k).
- Contribution Limits: The IRS sets limits on how much you can contribute each year. These limits often increase annually, and staying informed about the 2026 limits is crucial for maximizing your savings.
- Investment Options: Your 401(k) typically offers a selection of mutual funds, exchange-traded funds (ETFs), and target-date funds. Understanding these options is key to optimizing returns.
For 2026, it’s vital to keep an eye on the updated IRS contribution limits. While the official numbers for 2026 are usually released late in the preceding year, financial experts often project these limits. Historically, these limits tend to increase incrementally. For example, if the 2025 limit was $23,000 for those under 50, you might anticipate a slight increase for 2026, perhaps to $23,500 or $24,000. For those aged 50 and over, catch-up contributions provide an additional opportunity to save, which also typically sees annual adjustments. Being aware of these figures will be your first step to truly maximize your 401(k) 2026.
Strategy 1: Maximizing Your Contributions – The Foundation of Growth
The most direct way to boost your 401(k) balance is to contribute more. It sounds simple, but many individuals fall short of maximizing their contributions. Here’s how to ensure you’re putting in as much as possible:
A. Hit the IRS Contribution Limit (or as Close as Possible)
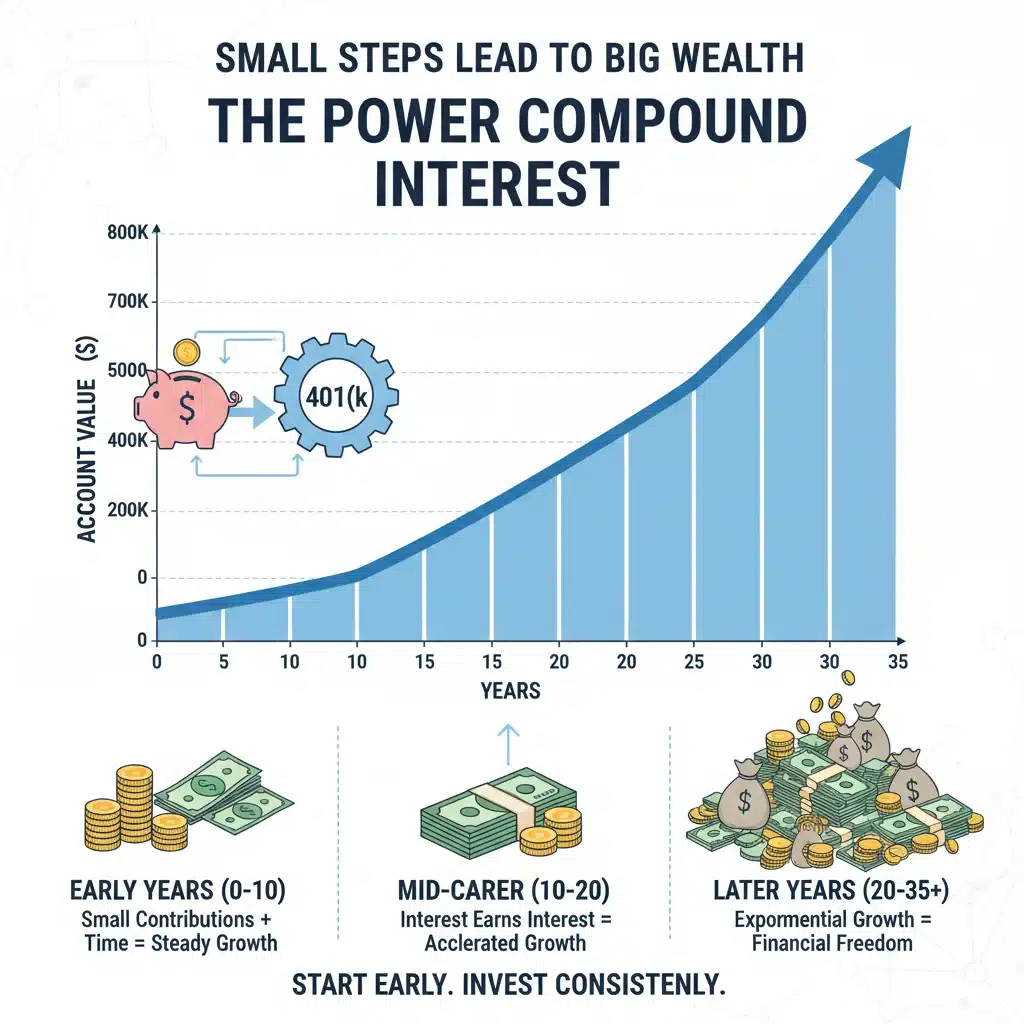
As mentioned, the IRS sets annual limits. For 2026, make it a priority to contribute up to this limit if your financial situation allows. This is the single most impactful action you can take to accelerate your retirement savings. If you can’t hit the maximum immediately, aim to increase your contribution percentage by at least 1-2% each year, especially when you receive a raise or bonus. Even small increases compound significantly over time.
B. Don’t Leave Free Money on the Table: Employer Match
This cannot be stressed enough: always contribute at least enough to get your full employer match. If your company offers a 50% match on the first 6% of your salary, and you only contribute 3%, you’re missing out on half of that free money. An employer match is an immediate, guaranteed return on your investment, often ranging from 50% to 100% on the matched portion. It’s literally free money that significantly boosts your savings power and is a critical component to maximize your 401(k) 2026.
C. Leverage Catch-Up Contributions (Age 50 and Over)
If you are age 50 or older by the end of 2026, you are eligible to make additional "catch-up" contributions above the standard limit. This provision is designed to help older workers who may have started saving later or want to accelerate their retirement funding. For example, if the standard limit is $23,500 and the catch-up contribution is $7,500, you could contribute a total of $31,000. These catch-up limits also tend to increase periodically, so verify the 2026 figures as they become available.
D. The Power of "The Raise Rule"
Implement the "raise rule" by automatically increasing your 401(k) contribution percentage whenever you get a pay raise. If you receive a 3% raise, consider increasing your contribution by 1-2%. You won’t miss the money because you never got used to having it, and your future self will thank you. This disciplined approach ensures your contributions grow proportionally with your income.
Strategy 2: Optimizing Your Investment Choices for Higher Returns
Contributing more is crucial, but how your money is invested within your 401(k) is equally important. Smart investment choices can significantly impact your returns and help you maximize your 401(k) 2026.
A. Understand Your Risk Tolerance and Time Horizon
Your investment strategy should align with your personal risk tolerance and how many years you have until retirement. Generally, younger investors with a longer time horizon can afford to take on more risk, investing in a higher percentage of equities (stocks) for potentially higher growth. As you get closer to retirement, it’s often prudent to gradually shift towards a more conservative allocation with a higher percentage of fixed-income investments (bonds) to protect your accumulated capital.
B. Diversification is Key
Don’t put all your eggs in one basket. Diversify your investments across different asset classes (stocks, bonds, real estate, etc.), industries, and geographies. Most 401(k) plans offer a selection of mutual funds that provide built-in diversification. Avoid concentrating too much of your portfolio in your company’s stock, even if it seems appealing. While it can be tempting, it ties your retirement savings too closely to the fortunes of a single entity.
C. Evaluate Fund Performance and Fees
Regularly review the performance of the funds available in your 401(k) plan. Compare their returns against relevant benchmarks and peer funds. Crucially, pay close attention to expense ratios. High fees, even seemingly small percentages, can erode a significant portion of your returns over decades. Opt for low-cost index funds or ETFs when available, as they often outperform actively managed funds over the long term due to their lower expense ratios. Lower fees directly translate to more money staying in your account to grow, helping you to maximize your 401(k) 2026.
D. Utilize Target-Date Funds (If Appropriate)
For investors who prefer a hands-off approach, target-date funds can be an excellent option. These funds automatically adjust their asset allocation over time, becoming more conservative as you approach your target retirement date. They offer built-in diversification and rebalancing, simplifying your investment strategy. Just ensure you choose a fund with a target date that aligns with your planned retirement year and review its underlying holdings and expense ratio.
E. Rebalance Your Portfolio Annually
Over time, market fluctuations can cause your portfolio’s asset allocation to drift from your desired targets. Rebalancing involves selling off some of your overperforming assets and buying more of your underperforming assets to bring your portfolio back to its original allocation. This practice helps manage risk and can even boost returns by forcing you to "buy low and sell high." Make it a habit to review and rebalance your 401(k) portfolio at least once a year.
Strategy 3: Leveraging Tax Advantages and New Regulations
The tax benefits of a 401(k) are a powerful tool for wealth accumulation. Understanding and utilizing them effectively is crucial to maximize your 401(k) 2026.
A. Traditional vs. Roth 401(k)
Many employers now offer both a traditional 401(k) and a Roth 401(k). The key difference lies in when you pay taxes:
- Traditional 401(k): Contributions are pre-tax, reducing your current taxable income. Withdrawals in retirement are taxed. This is generally beneficial if you expect to be in a lower tax bracket in retirement than you are now.
- Roth 401(k): Contributions are made with after-tax dollars, meaning they don’t reduce your current taxable income. However, qualified withdrawals in retirement are completely tax-free. This is often advantageous if you expect to be in the same or a higher tax bracket in retirement.
Consider your current income, projected future income, and tax bracket to decide which option (or a combination of both) is best for you. Some individuals choose to split their contributions between both types to hedge against future tax rate uncertainty.
B. Understanding SECURE Act 2.0 (and Future Changes)
The SECURE Act 2.0, enacted in late 2022, brought significant changes to retirement planning, many of which are being phased in over several years. While specific changes for 2026 are yet to be fully detailed, it’s important to stay informed about its provisions, which include:
- Increased Catch-Up Contribution Limits: For those aged 60-63, higher catch-up limits are being introduced.
- Automatic Enrollment and Escalation: More employers are being encouraged to automatically enroll employees in 401(k)s and increase contributions annually.
- Student Loan Match: Some plans may allow employers to make matching contributions based on employees’ student loan payments.
- Emergency Savings Accounts: New provisions allow for certain emergency savings accounts linked to retirement plans.
Staying updated on these legislative changes is paramount. Consult with your plan administrator or a financial advisor to understand how SECURE Act 2.0 and any subsequent legislation might impact your ability to maximize your 401(k) 2026.
C. Tax Loss Harvesting (Indirectly Related)
While not directly applicable within a 401(k) (as you can’t tax-loss harvest in tax-deferred accounts), understanding tax efficiency across your entire investment portfolio is important. If you have other taxable brokerage accounts, strategically harvesting losses can offset gains and even a portion of ordinary income, freeing up capital that could indirectly be used to boost your 401(k) contributions or other savings.
Strategy 4: Advanced Tactics and Regular Review
Beyond the core strategies, several advanced tactics and a commitment to regular review can further enhance your 401(k)’s performance.
A. Consolidate Old 401(k)s
If you’ve changed jobs multiple times, you likely have several old 401(k) accounts scattered across different providers. Consolidating these into your current 401(k) (if the plan allows) or rolling them over into an IRA can simplify your financial life, reduce fees, and give you a clearer overall picture of your retirement savings. This consolidation makes it easier to manage and maximize your 401(k) 2026 strategy.
B. Understand Vesting Schedules
Employer matching contributions often come with a vesting schedule, meaning you don’t fully "own" the matched funds until you’ve worked for the company for a certain period. Be aware of your company’s vesting schedule. If you’re considering leaving a job, understanding your vesting status can influence your departure timing to ensure you don’t forfeit any employer contributions.
C. Avoid 401(k) Loans and Early Withdrawals
While some 401(k) plans allow for loans or hardship withdrawals, these should be considered a last resort. Taking a loan means you’re paying interest to yourself, but you’re also missing out on potential investment growth on that money. Early withdrawals (before age 59½) typically incur a 10% penalty on top of ordinary income taxes, severely hindering your retirement savings progress.
D. Regular Review and Adjustment
Your 401(k) strategy isn’t a "set it and forget it" plan. Life changes, market conditions shift, and your financial goals evolve. Make it a habit to review your 401(k) at least annually. This review should include:
- Checking your contribution rate and increasing it if possible.
- Verifying your employer match.
- Reviewing your investment allocations and rebalancing if necessary.
- Assessing fund performance and expense ratios.
- Updating your beneficiary information.
This proactive approach ensures your plan remains aligned with your objectives and helps you continuously maximize your 401(k) 2026 and beyond.
Projecting Your 15% Boost: A Hypothetical Scenario
Let’s consider a hypothetical example to illustrate how these strategies could lead to a 15% increase in your 401(k) growth. Imagine an individual, Sarah, who is 35 years old, earns $70,000 annually, and currently contributes 8% of her salary ($5,600) to her 401(k). Her employer matches 50% of the first 6% of her salary, meaning she receives an additional $2,100 ($70,000 * 0.06 * 0.50). Her total annual contribution is $7,700.
Let’s assume her current investments yield an average annual return of 7%.
Baseline Scenario (No Changes):
- Annual Contribution: $7,700
- Assumed Return: 7%
The difference in balance after 10 years is $260,000 – $205,000 = $55,000. This represents a growth difference of approximately 26.8% ($55,000 / $205,000). While our target was 15%, these combined strategies demonstrate how easily you can exceed that goal, showcasing the immense power of consistent contributions and optimized investments to maximize your 401(k) 2026.
Maximization Strategies for a 15% Boost:
- Increase Personal Contribution: Sarah implements the "raise rule" and increases her contribution from 8% to 10% of her salary ($7,000). This is a $1,400 increase.
- Optimize Employer Match: She was already getting the full match, so no change here, but it highlights its importance.
- Investment Optimization: By rebalancing her portfolio, switching to lower-cost index funds, and slightly increasing her equity exposure (aligned with her risk tolerance), she manages to boost her average annual return from 7% to 8%. This 1 percentage point increase in return is significant over time.
New Scenario with Maximization:
- New Annual Contribution: $7,000 (personal) + $2,100 (employer match) = $9,100
- New Assumed Return: 8%
Let’s compare the growth over 10 years (assuming she continues with these contributions and returns):
Initial 401(k) Balance: Let’s assume Sarah has an initial balance of $50,000.
Baseline Projection (7% return, $7,700/year):
Using a compound interest calculator, after 10 years, her balance would be approximately $205,000.
Maximized Projection (8% return, $9,100/year):
Using a compound interest calculator, after 10 years, her balance would be approximately $260,000.
This example is simplified and for illustrative purposes only. Actual returns will vary based on market conditions, specific investments, and individual circumstances. However, it vividly demonstrates the substantial impact of proactive management.
Conclusion: Your Path to a Stronger Retirement in 2026 and Beyond
Taking proactive steps to maximize your 401(k) 2026 is one of the most impactful financial decisions you can make for your future. By consistently increasing your contributions, strategically optimizing your investments, understanding and leveraging tax advantages, and regularly reviewing your plan, you can significantly accelerate your retirement savings and build a more secure financial future. Remember, even small adjustments can lead to substantial gains over time, thanks to the miracle of compound interest.
Don’t let inertia hold you back. Start today by reviewing your current 401(k) statement, checking your contribution percentage, and exploring your investment options. If you’re unsure, consider consulting with a qualified financial advisor who can provide personalized guidance tailored to your specific situation and help you navigate the complexities of retirement planning. Your future self will thank you for the diligence and foresight you apply now. Make 2026 the year you truly take command of your retirement destiny.