For decades, filing taxes has been a ritual of frustration for many Americans, often involving a reluctant payment to a third-party software company just to settle up with the government. But what if the government itself offered a free, streamlined alternative? That question is no longer hypothetical. The IRS Direct File program has officially entered the arena, challenging a multi-billion dollar industry and promising a simpler path for millions of taxpayers.
This new system represents a core shift in the nation’s tax-filing landscape. After a successful pilot program, the IRS is exploring a broader rollout of its in-house, digital tax preparation and filing service. The core idea is to provide a no-cost option for individuals with straightforward tax situations, cutting out the commercial middlemen who have long profited from the tax code’s complexity. its success isn’t just a matter of federal ambition; it hinges on a complex patchwork of state-level cooperation and technological integration.
This article provides a broad look at the IRS Direct File program’s expanding reach. We’ll break down which states are participating, what the step-by-step filing process actually looks like for eligible taxpayers, and the significant benefits and challenges facing this initiative. More importantly, we’ll explore what this government-led push means for the future of tax season and whether it can deliver on its promise of a simpler, more equitable system for all.
The Current Landscape of IRS Direct File: What’s New?
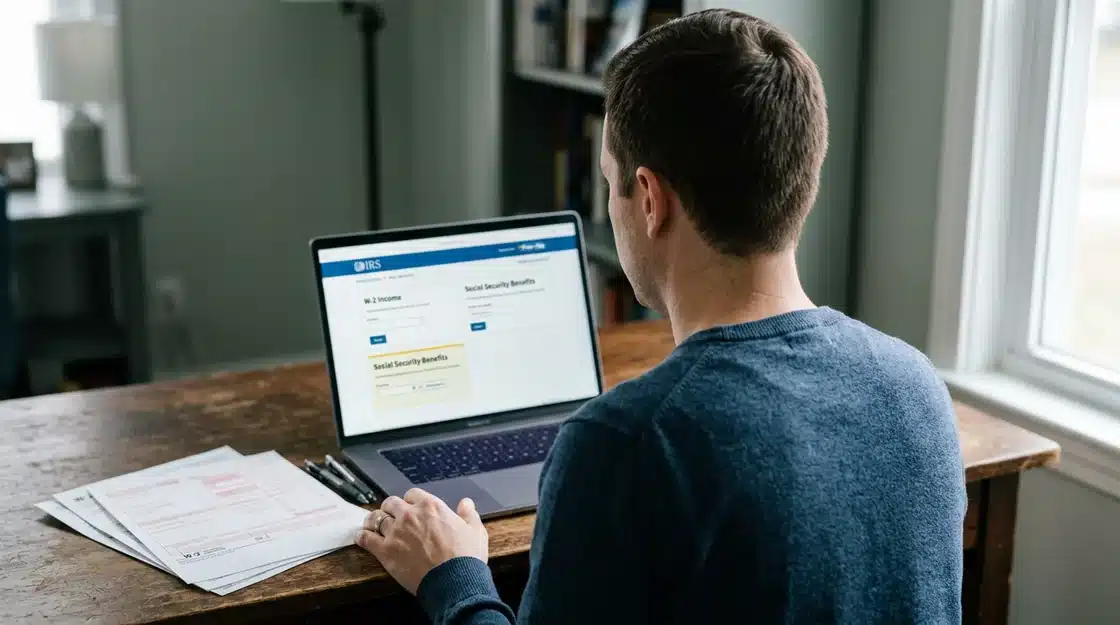
The federal government has officially entered the tax software business, and it’s already making waves. The IRS Direct File program recently concluded its initial pilot phase, offering a free, in-house tax filing option to a select group of taxpayers in 12 states. This wasn’t a full-scale rollout. Instead, think of it as a carefully controlled test drive designed for individuals with relatively simple tax situations, such as those with W-2 income, Social Security benefits, or unemployment compensation.
During this limited launch, the Internal Revenue Service reported that 140,803 taxpayers successfully filed their returns using the new system. What many taxpayers overlook is that this service was built from the ground up by the IRS itself (not a third-party contractor) to compete directly with commercial software. The central question now is whether this represents a genuine long-term alternative for millions of Americans.
From the federal perspective, the goal is straightforward: simplify tax filing and reduce costs for citizens who don’t need complex support. The system specifically handled common credits and deductions, including certain student loan interest deductions. it excluded more complicated scenarios, which often involve the new realities for gig workers and small business owners who manage variable income streams.
The initial pilot has proven the concept is viable on a federal level. But the program’s true test and future expansion hinge on a much more complicated factor: integrating with dozens of unique state tax systems.
States Embracing Direct File: An Evolving Map of Participation
The federal government built the Direct File system, but state participation is far from a given. Instead of a uniform rollout, we’re seeing a patchwork of adoption, with some states jumping on board while others watch from the sidelines. This creates a confusing landscape for taxpayers who were promised a simplified process. The success of this federal initiative surprisingly hinges on local politics and state-level IT capabilities.
Which States Offer Integrated Filing?
During the initial pilot phase, a select group of states partnered with the IRS to offer an integrated federal and state tax filing experience. This means taxpayers in these states could file both returns through a single, streamlined process. The Treasury Department estimated this initial group covered nearly 19 million eligible taxpayers.
The first wave of participating states included:
- Arizona: Integrated with the federal pilot, offering a state return option.
- California: Provided a pathway to its CalFile system after completing the federal return.
- Massachusetts: Offered an integrated state filing tool alongside the federal Direct File.
- New York: Partnered to guide users to its existing state free file program.
Residents in states with no state income tax—like Florida, Texas, and Washington—could use Direct File for their federal returns without needing a state component. This made the process exceptionally simple for them. What most people miss is how this creates a two-tiered system of simplicity depending entirely on your zip code.
Eligibility Requirements in Participating States
Simply living in a participating state doesn’t guarantee access. The pilot program had strict limitations on income types and tax situations. For the most part, eligibility was restricted to individuals with relatively simple tax returns, such as those with W-2 income, Social Security benefits, or unemployment compensation. This narrow focus excludes a huge portion of the modern workforce.
If you have more complex financial situations, you were likely left out. For example, the system generally did not support individuals with income from freelance work, which requires a different approach to quarterly estimated taxes for gig workers. The same goes for those itemizing deductions—a major hurdle for anyone trying to claim deductions for things like significant medical expenses or even the student loan interest deduction. Is this focus on “simple” returns serving the public, or just cherry-picking the easiest cases?
This state-by-state approach is creating a system of tax-filing “haves” and “have-nots,” where your ability to access a free, government-provided tool is dictated by state legislative priorities and bureaucratic inertia.
The challenge is building public trust in a system developed by the same entity that audits you.
— Dr. Ellen Vance, Senior Fellow at the Tax Policy Center
| Feature | Description | Key Consideration |
|---|---|---|
| Cost | Completely free to use for both federal and participating state returns. | Eliminates the average $250 fee charged by commercial tax prep services for similar returns. |
| Eligibility | Currently limited to taxpayers with simple returns (e.g., W-2 income, Social Security, unemployment). | Does not support itemized deductions, gig work income, or capital gains, excluding many filers. |
| State Integration | After filing the federal return, users are transferred to a partner state’s own free filing system. | The user experience and software quality can vary significantly between the federal and state platforms. |
| Support | Support is provided via live chat with IRS customer service representatives during specified hours. | This is for technical help with the software, not personalized tax advice. |
| Provider | Developed and maintained directly by the IRS, not a third-party contractor. | Raises questions about a potential conflict of interest between enforcement and taxpayer assistance. |
Navigating Direct File: A Step-by-Step Guide for Eligible Taxpayers
The promise of a free, government-run tax filing system is compelling, but the actual process can feel opaque. Using IRS Direct File isn’t like dropping a form in the mail; it’s an interactive digital process with specific checkpoints. Success hinges on preparation and understanding how the federal and state systems connect—or, in some cases, don’t.
Think of it less as a single application and more as a guided journey with a transfer point. It works. The key is knowing the route before you start.
Pre-Filing Checklist: What You Need
Before you even open the Direct File website, gathering your documents is the most critical step. Having everything on hand prevents frustrating stops and starts. The system requires precise data, and you won’t be able to save your progress indefinitely if you have to hunt for a missing form. What most people miss is that the identity verification step can take time, so it’s best to handle that early.
You will need the following items to complete your return:
- Social Security Numbers (SSN) or Individual Taxpayer Identification Numbers (ITIN) for yourself, your spouse, and any dependents.
- Income Documents: This includes Forms W-2 from employers, Forms 1099-INT for interest, and Forms 1099-DIV for dividends.
- Bank Account Information: Your bank’s routing number and your account number are required for receiving a direct deposit refund.
- Prior-Year Adjusted Gross Income (AGI): This is often used to verify your identity when you file electronically.
- A government-issued ID for the mandatory ID.me identity verification process, which is a prerequisite for using the system.
The Federal Filing Journey
Once you’ve passed the identity verification gate, the federal filing process begins. The Direct File system uses a straightforward question-and-answer format, walking you through sections on income, credits, and deductions. It’s designed specifically for taxpayers with relatively simple financial situations—meaning it won’t handle certain complexities. For instance, the system is not built for those who need to manage quarterly estimated taxes for gig workers or capital gains from investments.
As you input information from your W-2s and other forms, the software calculates your tax liability or refund in real-time. This allows you to see the immediate impact of entries like the student loan interest deduction. The entire experience is contained within the IRS platform. After a final review, you’ll sign and submit your federal return electronically.
State Integration: fluid or Separate?
Here is where the process can get confusing. Direct File does not have a built-in state tax filing component. Instead, for participating states, it acts as a bridge. After you successfully file your federal return, the system will prompt you with an option to continue to your state’s filing tool. This handoff is designed to be smooth, transferring your federal data to the state platform so you don’t have to enter everything twice.
This is not a single, unified program. It is a sequence. The underrated factor here is that you are now using a completely different piece of software maintained by your state’s revenue department, with its own interface and support system.
Understanding State-Specific Nuances
Once you land on your state’s tax tool, you’ll find it has its own set of questions. States have unique tax laws, credits, and deductions that don’t exist at the federal level. For example, you might be asked about property tax credits, renter’s rebates, or specific state-level educational savings accounts. According to a recent pilot program report by the Treasury Inspector General for Tax Administration, while 91% of users successfully filed their federal return, the state-level completion rate was slightly lower at 86%, suggesting some filers encounter friction at this stage.
Is your state’s tool as user-friendly as the federal one? That can vary widely. Be prepared to answer questions that seem redundant but are necessary for state calculations—this is especially true for verifying dependents or residency status for the full tax year.
Post-Submission: What to Expect
After submitting both returns, you should receive separate confirmation emails from the IRS and your state’s tax agency. These are your proof of filing. From there, you can track the status of your federal refund using the “Where’s My Refund?” tool on the IRS website, typically within 24 hours of acceptance. States offer similar tracking tools on their own revenue department websites.
While the IRS issues most refunds in under 21 days, state processing times can differ significantly depending on their resources and fraud-detection protocols. The journey isn’t over until the money is in your account, and keeping an eye on both federal and state trackers is the final step in this new filing landscape.
Benefits and Challenges: A Balanced Perspective on Direct File’s Evolution
The push for a government-run tax filing system isn’t new, but its actual implementation forces a stark question: is this a genuine public service or a bureaucratic overreach? For millions of Americans with simple tax returns, the program promises a streamlined, no-cost alternative to commercial software. The appeal is undeniable, cutting through the noise of up-sells and confusing pricing tiers that define the private tax-prep market.
But what most people miss is the quiet tension brewing beneath the surface. This isn’t just about free software; it’s a underlying challenge to a multi-billion dollar industry that has profited from complexity for decades. The program’s success or failure will likely hinge on its ability to navigate this political and technical minefield.
Key Advantages for Taxpayers
The most immediate and obvious benefit of the IRS Direct File state expansion is cost. It’s completely free. A recent analysis from the Consumer Federation of America found that taxpayers spent an average of $250 on tax preparation services for relatively simple returns. The Direct File system eliminates this cost entirely, putting money directly back into the pockets of households that need it most.
This is a major shift. Beyond the price tag, the integration of state and federal returns into a single, cohesive process removes a significant point of friction. Instead of completing federal taxes and then re-entering much of the same information into a separate state platform, the system aims for a one-and-done experience. This is especially beneficial for those with straightforward income sources, like W-2 employees or retirees, as well as some independent contractors navigating new realities for quarterly estimated taxes.
Simplification also reduces the cognitive load and stress associated with tax season. By pre-populating information the IRS already has on file—like wages and withholdings reported by employers—the system acts less like a blank form and more like a verification tool. It’s a core shift from data entry to data confirmation.
Overcoming the Hurdles: Challenges and Criticisms
Despite the clear upsides, the road ahead for Direct File is littered with obstacles. The program is currently limited to taxpayers with very specific, simple financial situations. It does not accommodate itemized deductions, capital gains, or certain types of retirement income, forcing many to return to paid software. What happens when a user has a slightly more complex issue, like figuring out the nuances of the student loan interest deduction?
Critics, primarily from the tax software industry, argue the IRS has a conflict of interest. Can an agency responsible for enforcement also be trusted to provide neutral, taxpayer-first filing assistance? The argument is that the IRS’s primary goal is revenue collection, not helping you find every last deduction—a fair point that deserves scrutiny. Dr. Ellen Vance, a senior fellow at the Tax Policy Center, notes, “The challenge is building public trust in a system developed by the same entity that audits you.”
There are also significant technical hurdles. Building and maintaining a secure, user-friendly platform that serves millions and integrates with dozens of unique state tax systems is a monumental task. The initial pilot program was small by design, but scaling it nationwide will test the IRS’s technical capabilities, especially when dealing with complex life events that can impact taxes, such as navigating the fallout from medical debt. The entire project is a bit like your local DMV promising to build a self-driving car; the ambition is there, but the core expertise is in something else entirely. The ultimate question is whether this public option can evolve quickly enough to remain relevant or if it will become another well-intentioned but limited government tech project.
The Future of Direct File: Projections and Potential Impact on Tax Season
The initial pilot of IRS Direct File was more than just a test run; it was a shot across the bow of the multi-billion dollar tax preparation industry. Its survival and expansion aren’t guaranteed, but the program’s trajectory suggests a underlying shift in how Americans interact with the tax system. This isn’t just about free software. It’s about control.
Expanding to More States: What’s Next?
The initial dozen states were just the beginning. The real test for IRS Direct File state expansion involves convincing states with more complex income tax laws and entrenched political opposition to join the fold. Tax policy experts predict a cautious, phased rollout, targeting states with relatively simple tax structures and existing technological capacity first. Think states with flat taxes or those that largely conform to federal definitions of income.
According to analysis from the Center on Budget and Policy Priorities, integrating a state like Pennsylvania, with its local earned income taxes, would present a significantly higher technical hurdle than a state like Colorado. The political calculus is just as tricky. State revenue departments must be willing partners, and lobbying from commercial tax prep companies remains a formidable obstacle. The underrated factor here is voter demand — if taxpayers see a simplified, no-cost option succeeding elsewhere, the pressure on state lawmakers could become immense.
New Features and Broader Eligibility
The current iteration of Direct File is intentionally limited, focusing on simple W-2 income and standard deductions. The next logical step is to broaden its appeal. This likely means incorporating more common tax situations, such as interest and dividend income, or certain educational credits. Expanding its capabilities is a delicate balancing act; add too much complexity too quickly, and the system could become as confusing as the commercial products it aims to replace.
One potential pathway involves integrating data from other government programs. Imagine a system where tax information could seamlessly pre-populate financial aid forms. This could dramatically simplify the process for millions of families trying to navigate FAFSA verification and secure college funding. It’s a powerful vision of a more connected government service ecosystem.
Beyond Simple Returns: Complexities on the Horizon?
Handling a simple W-2 is one thing. But what happens when the program attempts to accommodate the modern workforce? The biggest challenge — and opportunity — for Direct File is tackling the gig economy. Incorporating 1099-NEC and 1099-K income, along with the associated deductions and expenses, is a monumental leap in complexity.
This would require a system that can guide freelancers and independent contractors through the often-confusing world of self-employment tax. It would also directly compete with software services that have built their business models around serving this exact demographic. Can a government tool handle the nuances for people who need to understand new realities for gig workers and estimated payments? The IRS’s ability to solve this puzzle will determine if Direct File remains a niche tool or becomes a universal platform.
Shifting the Tax Software Landscape
Let’s be blunt: Direct File is an existential threat to the dominant players in the tax software market. For decades, companies like Intuit (TurboTax) and H&R Block have profited from a tax code they lobbied to keep complicated. The market functions like a soda aisle dominated by two major brands, with the IRS now introducing a generic, no-cost alternative. It might not have all the fancy features, but it gets the job done for a huge portion of the population.
A recent report from the National Taxpayers Union suggests that if Direct File expanded to cover just 50% of eligible filers, it could erode commercial software’s market share by up to 25% within five years. This pressure will likely force commercial providers to compete on features for more complex returns, potentially lowering prices for their basic services. The “freemium” models that often lead to surprise up-charges could become a thing of the past.
Long-Term Vision for Taxpayer Services
The ultimate goal for many advocates of Direct File is a system of “return-free filing,” where the IRS uses information it already has from employers and financial institutions to prepare a pre-filled return for a taxpayer’s approval. This is already the standard in dozens of other countries. It transforms tax season from a stressful data-entry task into a simple review-and-confirm process.
Achieving this vision requires a massive investment in IRS modernization and a significant cultural shift. It means taxpayers would trust the agency to get it right, while still having the ability to make adjustments for things like charitable donations or claiming the deduction for student loan interest. While return-free filing is still years away in the United States, every expansion and new feature added to Direct File is another foundational block being laid for that future.
Required Considerations Before Using Direct File
The promise of free, government-run tax filing is compelling, but Direct File is not a universal solution. Before jumping in, you must determine if your financial situation fits within its deliberately narrow guardrails. The system is built for taxpayers with relatively simple returns—think W-2 income, Social Security benefits, and the standard deduction.
This isn’t for everyone.
According to IRS data, nearly 89% of filers take the standard deduction, making a large portion of the population technically eligible. But is your financial life simple enough for the government’s free tool? If you’re a gig worker juggling multiple 1099s, you’ll need to stick with traditional software, especially when sorting out quarterly estimated tax payments. Even common deductions for things like student loan interest are included, but itemized deductions are a non-starter.
Before committing, run through this mental checklist:
- Income Sources: Is your income limited to W-2s, Social Security, unemployment benefits, and interest of $1,500 or less?
- Deductions: Are you planning to take the standard deduction?
- Credits: Do you only claim common credits like the Earned Income Tax Credit or the Child Tax Credit?
- Support Needs: Are you comfortable with live chat support during specified hours instead of phone calls or in-person help?
Understanding the support system is critical. The assistance is text-based and limited to technical issues and basic tax law questions within the platform’s scope. It’s like having a detailed recipe but no experienced chef to call when you get stuck. The burden of correctness still falls squarely on your shoulders, and knowing when your return is too complex for the tool is the most important prerequisite.
Is This the End of Tax Season as We Know It?
The expansion of IRS Direct File is more than a technical update; it’s a referendum on the public’s relationship with the tax system. For years, complexity has been the moat protecting a lucrative private industry. By building a public bridge over that moat, the IRS is implicitly stating that filing taxes should be a civic duty, not a consumer transaction. The initial data and user feedback suggest a strong appetite for this alternative, but the program’s future is far from certain.
The real test will come not from scaling servers, but from navigating political opposition and the bureaucratic inertia of dozens of state tax agencies. Can a government agency out-innovate the private sector it aims to disrupt, especially when its scope is intentionally limited to ‘simple’ returns? The answer will determine whether Direct File becomes a cornerstone of modern tax administration or a niche tool for a select few.
Ultimately, the program forces us to ask a core question: Should the same entity that collects our taxes also be responsible for helping us file them? As Direct File continues to evolve, your answer to that question may very well shape the future of how every American interacts with the IRS.
Frequently Asked Questions About IRS Direct File
What is the IRS Direct File program?
IRS Direct File is a free, online tax preparation and filing service developed and run by the Internal Revenue Service. It is designed to provide a no-cost alternative to commercial tax software for taxpayers with relatively simple financial situations, allowing them to file their federal tax returns directly with the government.
Which states currently participate in the IRS Direct File program for state taxes?
During its pilot phase, several states offered integrated or linked state filing options, including Arizona, California, Massachusetts, and New York. residents of states with no income tax, such as Florida, Texas, and Washington, could use it for their federal-only filing needs. The list of participating states is expected to evolve as the program expands.
Is IRS Direct File suitable for all taxpayers?
No, the program is not suitable for everyone. It is specifically designed for individuals with simple tax returns, such as those with W-2 income, Social Security benefits, or standard deductions. It does not currently support more complex situations like itemized deductions, freelance or gig work income, or investment gains.
How does IRS Direct File compare to commercial tax software?
The main difference is cost—Direct File is completely free, whereas commercial software often has fees for filing or accessing certain forms. commercial software typically supports a much wider range of complex tax situations, offers more solid features, and may provide different levels of tax advice or audit support that Direct File does not.
What kind of support is available if I encounter issues using Direct File?
The IRS provides support for Direct File users through a live chat feature on the platform. IRS customer service representatives are available during designated hours to help with technical questions about using the software. This support does not include personalized tax advice or guidance on complex tax law interpretations.